
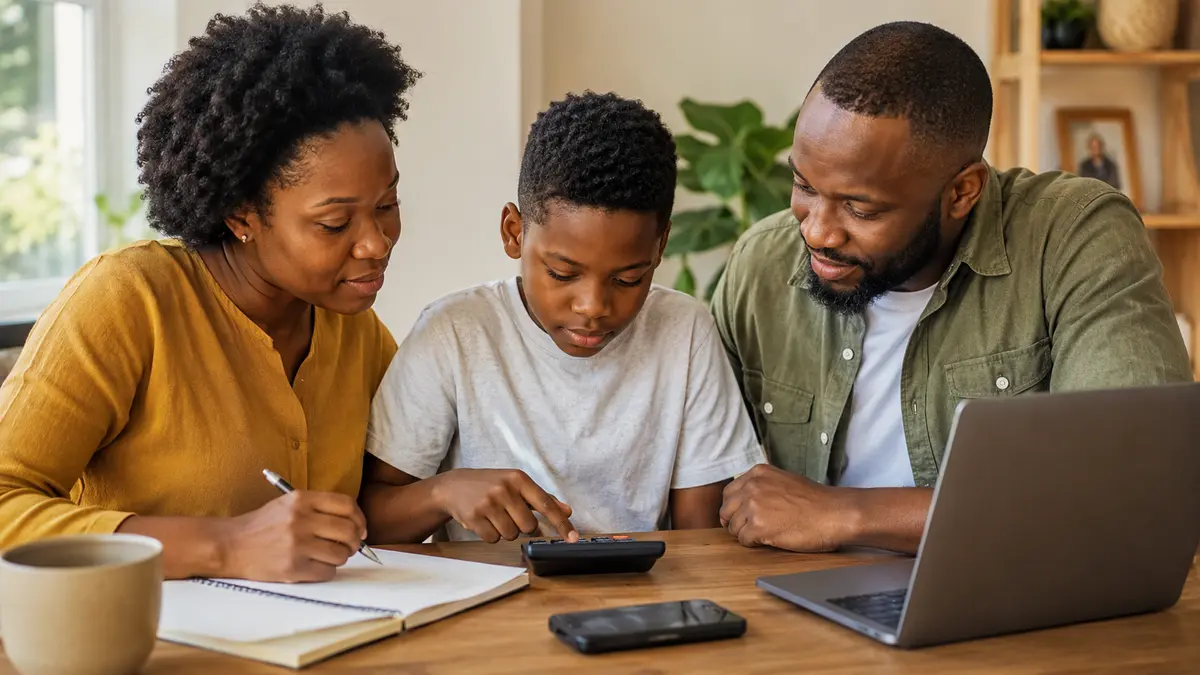
Family Finance Africa starts with one reality: families cannot budget their way around every low-income, inflation or economic shock. But households can still improve resilience by making money visible, controlling what they can, planning predictable costs and teaching children age-appropriate financial habits.
This guide is general financial education, not individualized investment, tax or insurance advice. Products, regulations, currencies and risks differ by country, so verify decisions with appropriately qualified local professionals where necessary.
Family Finance Africa: 9 smart steps
1. Know your real monthly numbers
Start with income that actually reaches the household, then list essential costs, debt payments, school expenses, transport, food, housing, healthcare, support to extended family and discretionary spending. Annual expenses should not disappear from the plan simply because they are not due this month. Divide predictable yearly costs into monthly targets.
2. Separate fixed, flexible and irregular costs
This makes cuts more intelligent. Rent may be fixed in the short term, groceries flexible within limits, and school uniforms irregular but predictable. When everything is lumped together, households may focus on tiny purchases while missing the larger cost drivers.
3. Build an emergency buffer in stages
A large emergency fund can feel impossible. Start with a smaller target tied to one realistic disruption, such as urgent transport, a basic medical cost or a temporary income gap. Once that buffer exists, expand it gradually. Keep emergency money somewhere accessible enough for genuine emergencies but separate enough to reduce casual spending.
4. Plan education costs years, not weeks, ahead
School fees are only part of education spending. Include transport, uniforms, books, devices, exams, tutoring and transitions between school stages. For future university costs, research likely pathways early and revisit assumptions yearly. Our STEM Education Africa guide also shows how valuable learning can happen without equating quality with expensive equipment.
5. Protect the household against catastrophic risks
Depending on your country and circumstances, appropriate health coverage, life insurance, disability protection or other risk tools may matter. Do not buy a product only because a salesperson calls it an “investment.” Understand exclusions, fees, claims conditions and whether the provider is regulated locally before committing.
6. Teach children with real, small decisions
Children learn money habits through experience and observation. Give age-appropriate opportunities to compare prices, plan a small budget, save toward a goal or decide how to divide limited money. OECD analysis of PISA data notes that students develop financial literacy through school, interactions with parents and friends, and personal experiences with money.
7. Separate saving from investing
Savings for near-term needs generally require stability and accessibility. Investing normally involves uncertainty and a longer horizon. The correct balance depends on goals, risk, local inflation, regulation and available products. Before chasing returns, understand what you own, the fees, the risks and how easily you can access the money.
8. Plan for extended-family obligations honestly
For many African households, financial responsibility extends beyond the nuclear family. Pretending these transfers will not happen produces unrealistic budgets. Decide what support your household can sustainably provide, communicate boundaries respectfully, and avoid repeatedly sacrificing essential needs or high-priority goals to unplanned requests.
9. Hold a short monthly money meeting
Review what changed, which bills are coming, progress toward savings goals and where spending drifted. Keep the meeting factual rather than accusatory. Money systems improve when couples or household decision-makers can discuss trade-offs without hiding information or turning every variance into a moral failure.
A simple four-bucket family system
- Today: regular living expenses.
- Protection: emergency reserves and appropriate risk protection.
- Tomorrow: education, major goals and long-term saving/investing.
- Choice: discretionary spending and giving.
The percentages will differ radically between households. The value is the separation itself: every unit of income has a job before it disappears.
How to teach money skills by age
Young children: practise counting, waiting and choosing between two affordable options. School-age children: introduce small budgets, saving goals and price comparison. Teenagers: discuss bank accounts, digital scams, interest, borrowing, earning, taxes and the difference between wants, needs and social pressure.
OECD research on parents and students’ financial literacy supports the role of family interaction in building money capability.
Frequently asked questions
How much should an African family save?
There is no universal percentage. Income stability, debt, dependants, local costs and goals vary. Start with a sustainable amount and increase it when capacity improves.
Should education savings come before an emergency fund?
Both matter, but a basic emergency buffer can prevent an unexpected cost from repeatedly destroying longer-term savings. Households can then build goals in parallel according to priorities.
How early should children learn about money?
Simple concepts such as choice, waiting and saving can begin in childhood and become more sophisticated with age.
Is investing always better than saving?
No. Near-term money and emergency funds may need liquidity and lower volatility, while longer-term goals may tolerate more risk. The right choice depends on the goal and local options.
Strong finances support strong parenting, but money is a tool rather than the goal. Use this Family Finance Africa framework alongside our African Parenting Guide to align household resources with the future you want to build.